

1
Fill out the form below, and we will get in touch with you as soon as possible to provide the information or assistance you need.
2
Contact us for quotes or inquiries through our communication channels. ¡We are at your service!


3
Stay up to date with news, articles, and important information. Visit us, follow us, and like our social media pages to stay informed and receive updates!


4
Schedule a meeting with one of our expert advisors to discuss your needs.
-

Asicon Consulting
We transform your administrative, technological, and process needs into effective solutions.
Sitemap
Contact us
-
Asicon Consulting
- All rights reserved © (2019 - 2026)
- SSL active - Protected data
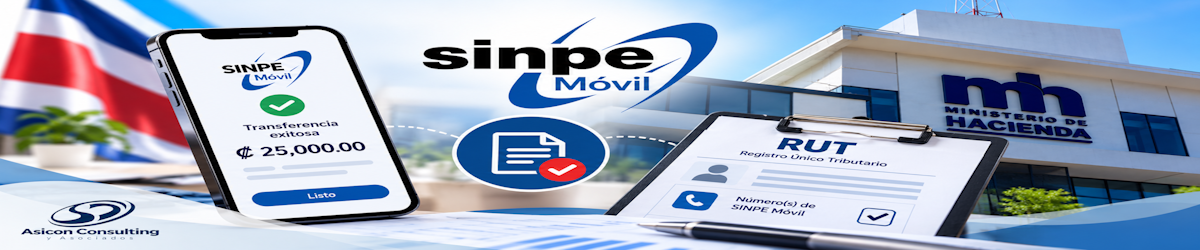
On October 16th, Executive Decree No. 45953-H was published, establishing a new requirement for taxpayers who use SINPE Móvil to receive payments related to economic activities. This provision takes effect as of the date of publication and requires taxpayers to register the SINPE Móvil numbers used in their economic activities.
For taxpayers who are already registered, the 12-month period begins when the corresponding general resolution takes effect. It is important to identify now the numbers used to receive payments, the associated accounts, and how these transactions are being reconciled with electronic invoicing and accounting records.
The implementation of this requirement seeks to improve transparency and tax oversight of transactions carried out through SINPE Móvil, thereby supporting compliance with applicable tax obligations.
New Requirement for SINPE Móvil Users
The Ministry of Finance has established a new requirement for taxpayers who use telephone numbers linked to SINPE Móvil as a payment method within their economic activities.
Executive Decree No. 45953-H was published on October 16, 2026, and amends Article 22 of the Tax Procedure Regulations to incorporate the registration of SINPE Móvil numbers used in economic activities.
Taxpayers must report the telephone number or numbers linked to bank accounts through SINPE Móvil when these are used as a payment method to receive income related to their economic activity.
Who does this apply to?
Companies or businesses that receive customer payments through SINPE Móvil.
Individuals who receive payments for their services or professional fees through a SINPE Móvil number.
Taxpayers who use SINPE Móvil to receive income related to their economic activity.
Companies that incorporate SINPE Móvil as part of their payment collection methods.
Do personal SINPE Móvil numbers also have to be registered?
The requirement does not mean that all personal telephone numbers must be registered with the Ministry of Finance.
The relevant criterion is how the number is used. If a personal number is also used to receive customer payments, sales proceeds, or payments for services related to an economic activity, it must be considered under this new requirement.
If a taxpayer uses several SINPE Móvil numbers to receive payments related to their economic activity, each one should be considered as part of the corresponding registration process.
Where will the information be registered?
The information must be incorporated into the Single Taxpayer Registry (RUT) as part of the taxpayer's relevant tax information.
They must provide the corresponding information during the registration process, according to the mechanisms established by the Ministry of Finance.
They must make the corresponding update or modification to their RUT once the procedure is enabled by the Tax Administration.
Important deadlines
Publication of Executive Decree No. 45953-H in the Official Gazette, La Gaceta.
The Tax Administration must make the necessary adjustments to forms and systems and issue the general resolution establishing the operational procedure.
The deadline will be 12 months from the effective date of the general resolution establishing the procedure.
The 12-month period should not be counted directly from October 16, 2026. Existing taxpayers must wait for the corresponding general resolution to take effect.
What must the Ministry of Finance do before implementing the registration process?
Incorporate the new information into the forms related to registration and modification of the RUT.
Make the necessary technological changes to allow the registration of the corresponding telephone numbers.
Define the procedure and operational requirements that taxpayers must follow.
SINPE Móvil, RUT and Electronic Invoicing
The new requirement is part of a broader process aimed at increasing the traceability of electronic payment methods used by taxpayers.
The identification of the SINPE Móvil number used for commercial purposes is related to the information registered in the RUT and the data generated through electronic invoicing, including the identification of the corresponding payment method.
This will provide the Tax Administration with additional information that can be used to compare the payment methods used with electronic invoices and the income reported by taxpayers.
Does this create a new tax?
No. Executive Decree No. 45953-H establishes a formal tax reporting and control requirement. It does not create a new tax on transfers made through SINPE Móvil.
Tax obligations continue to depend on the nature of the economic transaction, not on the payment method used. A product or service subject to taxes remains subject to the applicable tax obligations regardless of whether the customer pays in cash, by card, bank transfer, or SINPE Móvil.
Is there a limit of 100 SINPE Móvil transfers per month?
There is no legal limit of 100 transfers per month.
The number of transfers received does not automatically determine that a commercial activity exists, nor is it the criterion established by this new requirement.
The relevant factor is the use of the telephone number as a payment method within an economic activity.
Can the Tax Administration audit income received through SINPE Móvil?
The new regulation strengthens the information available to the Tax Administration for purposes of tax management, control, and auditing.
Identifying the number used commercially may facilitate comparisons between payments received, electronic invoices, reported income, and other available tax information.
However, receiving a transfer through SINPE Móvil does not, by itself, prove that it represents a taxable sale or service. Transfers may also correspond to loans, transfers between one's own accounts, reimbursements, contributions, or other transactions that should be properly supported when applicable.
The importance of reconciliation
Verify that received transactions correspond to actual sales or services provided.
Compare invoiced amounts with the income actually received.
Verify that SINPE Móvil is correctly identified as the payment method when applicable.
Keep the documentation or information necessary to support transactions that do not correspond to income from sales or services.
What happens if the SINPE Móvil number changes?
Since the number used commercially will form part of the taxpayer's registered information, any change should be reflected through the RUT update mechanisms established by the Tax Administration.
For this reason, it is advisable to keep the information related to the payment methods used by the business up to date.
What happens if the requirement is not met?
Executive Decree No. 45953-H links non-compliance with this requirement to the applicable sanctions for failures related to the provision of information.
Article 83 of the Code of Tax Procedures and Regulations establishes sanctions for non-compliance related to the provision of information.
The penalty may reach 2% of the gross income from the previous fiscal period, subject to the limits and conditions established by law.
The application of any sanction must take into account the deadlines established for implementation of the new requirement and the applicable transitional period.
What do we recommend to taxpayers?
Determine which telephone numbers you currently use to receive payments related to your economic activity.
Verify the bank accounts linked to the numbers used to receive payments.
Verify that your business tax information is up to date.
Clearly identify which numbers are used exclusively for personal purposes and which are used to receive payments related to the economic activity.
Maintain consistency between SINPE Móvil payments received, electronic invoices, and accounting records.
Monitor the general resolution that will be issued by the Ministry of Finance and the final procedure for completing the registration.
Common mistakes to avoid
The new provision establishes an information requirement, not a new tax on transfers.
The requirement focuses on numbers used as a payment method within an economic activity.
There is no legal limit of 100 monthly transactions established by this regulation.
For existing taxpayers, the 12-month period begins when the corresponding general resolution takes effect.
It is important to maintain consistency between received transactions, electronic invoicing, and accounting records.
The nature of each transaction should be analyzed and, when applicable, supported with documentation that allows it to be properly justified.
Important Information
Executive Decree No. 45953-H has been published and establishes the new reporting requirement related to SINPE Móvil numbers used in economic activities.
However, for taxpayers who are already registered, the general resolution establishing the operational procedure must still be issued. This resolution will trigger the 12-month period for completing the registration.
Recommendation: Do not wait until the deadline approaches. Identify now the numbers used to receive payments, the associated bank accounts, and how these transactions are being reconciled with electronic invoicing and accounting records.